General liability insurance for contractors pays third-party bodily injury and property damage claims, plus defense costs: many public owners require $1,000,000 per occurrence and $2,000,000 aggregate, and the policy excludes employee injuries and repairing your own work.
Key takeaways
- The standard contractor policy is the ISO Commercial General Liability Coverage Form CG 00 01 04 13: Coverage A (bodily injury and property damage), Coverage B (personal and advertising injury) and Coverage C (medical payments up to the medical expense limit, regardless of fault).
- Defense costs sit on top of the limits: the form’s Supplementary Payments clause says these payments “will not reduce the limits of insurance” (CG 00 01 04 13, pages 8 to 9).
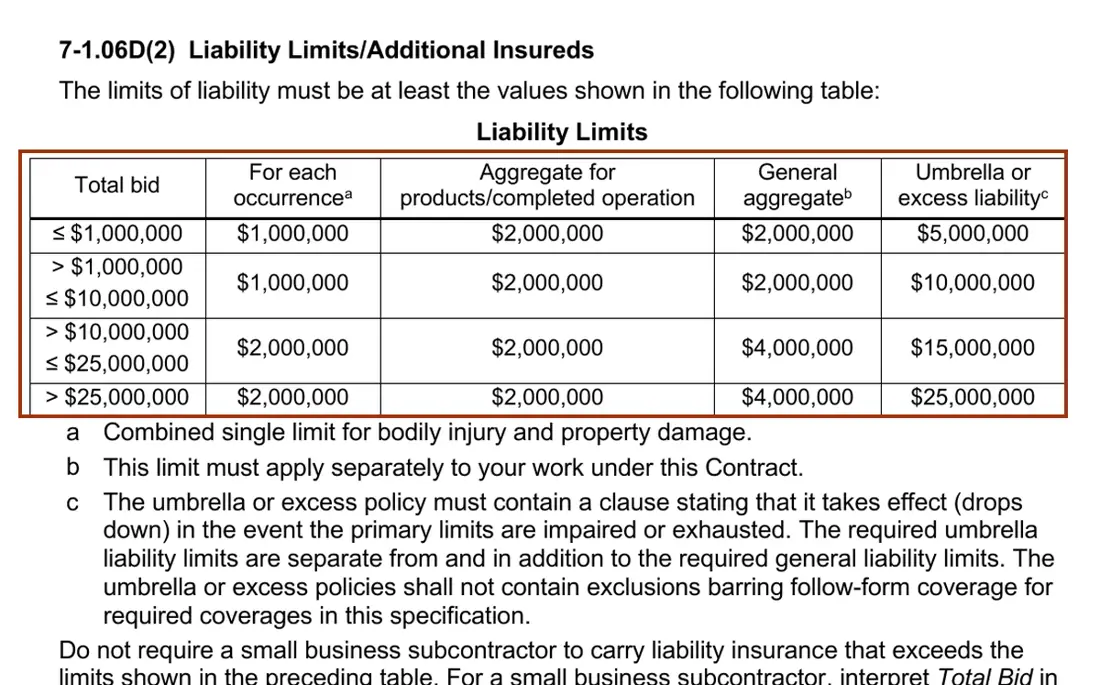
- On California state highway work, Caltrans Standard Specifications 7-1.06D(2) (revised 08-2025) require $1,000,000 per occurrence and $2,000,000 aggregate up to a $10,000,000 bid, $2,000,000 and $4,000,000 above it, plus a $5,000,000 to $25,000,000 umbrella.
- State licensing floors are far lower than project limits: Florida asks general contractors for $300,000 of public liability and $50,000 of property damage cover (Fla. Admin. Code R. 61G4-15.003), and Mississippi asks commercial licensees for $300,000 per occurrence (MSBOC).
- No regulator publishes a price list for contractor liability cover, but the BLS producer price index for non-auto liability insurance rose 10.0% from September 2025 to September 2026 and 33.0% from 2016 to 2025.
- On three California highway projects, contractors’ general liability, workers’ comp and excess premiums came to 0.40% to 1.71% of project value (Caltrans report to the Legislature, April 2009).
What does general liability insurance for contractors cover?
A contractor’s commercial general liability (CGL) policy pays damages the contractor is legally obligated to pay to other people for bodily injury, property damage and personal and advertising injury, and it pays to defend those suits. Most policies use the ISO CG 00 01 04 13 occurrence form, which Caltrans names as the acceptable standard in Standard Specifications section 3-1.07. The form has three coverages and six limits.
| Part of CG 00 01 04 13 | What it pays | Trigger | Limit that caps it |
|---|---|---|---|
| Coverage A: bodily injury and property damage | Damages for injury to people and physical damage to their property, plus defense | Injury or damage caused by an “occurrence” in the coverage territory and occurring during the policy period (Section I, 1.b) | Each occurrence limit, inside the general aggregate or the products-completed operations aggregate |
| Coverage B: personal and advertising injury | Libel, slander, false arrest, wrongful eviction, use of another’s advertising idea (definition 14) | Offense committed in the coverage territory during the policy period | Personal and advertising injury limit, inside the general aggregate |
| Coverage C: medical payments | Medical expenses of an injured member of the public, regardless of fault | Accident during the policy period; expenses reported within one year | Medical expense limit per person |
| Supplementary Payments | Defense expenses, court costs, post-judgment interest, up to $250 a day of the insured’s lost earnings while helping the defense | Any claim or suit the insurer defends | None: these payments do not reduce the limits |
| Section III limits | General aggregate; products-completed operations aggregate; each occurrence; personal and advertising injury; damage to premises rented to you; medical expense | Limits apply to each annual policy period | Shown on the declarations page |
“Occurrence” means an accident, including continuous or repeated exposure to the same harmful conditions (definition 13). The coverage territory is the United States, its territories, Puerto Rico and Canada. A passer-by hit by a falling block, a neighboring roof damaged by your crane, or a tenant’s flooded suite below your plumbing work are the Coverage A claims the form is built for.
The figures below recur through this page.
| Figure | What it is | Source |
|---|---|---|
| $1,000,000 / $2,000,000 | Each occurrence / general aggregate in a 2026 AIA A101 Exhibit A filled in by Anderson County, Texas | Exhibit A §A.3.2.2.1 |
| $2,000,000 / $4,000,000 | Caltrans each occurrence / general aggregate for bids over $10,000,000 | Caltrans 7-1.06D(2), 08-2025 |
| $5,000,000 to $25,000,000 | Caltrans umbrella or excess limit, by bid size | Caltrans 7-1.06D(2) |
| $500,000 | Federal minimum bodily injury cover per occurrence for work on a government installation | FAR 28.307-2(b)(1), FAC 2026-01 |
| $300,000 / $50,000 | Florida general and building contractor license: public liability / property damage | R. 61G4-15.003 |
| 10.0% | Rise in the BLS liability insurance price index, Sept 2025 to Sept 2026 (preliminary) | BLS PPI PCU524126524126403 |
| 7 years | Florida statute of repose for construction defect suits | Fla. Stat. §95.11(3)(b) |
What does a contractor’s CGL policy exclude?
CG 00 01 04 13 lists 17 Coverage A exclusions (a to q). For contractors, five matter most: injuries to your own employees (d and e) go to workers’ compensation; vehicle claims (g) go to commercial auto; pollution (f) needs separate cover; and damage to the work itself is cut back by exclusions j, k, l and m. Read the endorsements too: owners on AIA Exhibit A §A.3.2.2.2 ban 11 added exclusions.
| Exclusion in CG 00 01 04 13 | What it removes | Exception that matters to contractors |
|---|---|---|
| b. Contractual liability | Liability you take on by contract | Liability assumed in an “insured contract”, which includes the part of a contract where you assume another party’s tort liability (definition 9.f) |
| d. and e. Workers’ comp and employer’s liability | Injury to your own employees | Liability assumed under an insured contract (e) |
| f. Pollution | Discharge or release of pollutants | Building heating equipment fumes; hostile fire; contractors’ work for an owner added as additional insured, for ongoing operations |
| g. Aircraft, auto or watercraft | Vehicles you own, rent or operate | Parking others’ autos on your premises; watercraft under 26 feet you do not own |
| j(5) | The particular part of real property you or your subcontractors are working on, if the damage arises from those operations | None; this is the builder’s risk gap |
| j(6) | The particular part of property that must be repaired because your work was incorrectly performed on it | Does not apply to property damage in the products-completed operations hazard |
| l. Damage to your work | Damage to your completed work arising out of it | Does not apply if the damaged work, or the work causing the damage, was performed by a subcontractor |
| m. Impaired property | Property not physically injured, or impaired by your defective work or late performance | Loss of use after sudden, accidental injury to your work once in use |
Does general liability pay to fix your own faulty work?
Usually not for the faulty work itself, but often for what it damages. Exclusion j(6) removes repair of the part you performed incorrectly while work is ongoing, and exclusion l removes damage to your completed work. Exclusion l stops at work a subcontractor performed, which is why AIA Exhibit A §A.3.2.2.2.2 forbids policies that delete that subcontractor exception by endorsement.
Whether defective work is an “occurrence” at all (definition 13: an accident) is decided by state courts, and states have answered it differently. The practical step is to check the declarations and endorsement schedule for forms that delete the subcontractor exception or add residential, roofing or EIFS (synthetic stucco) exclusions, the items listed in Exhibit A §A.3.2.2.2.7 to .9.
Occurrence or claims-made: which form do owners accept?
Owners usually require the occurrence form. CG 00 01 pays for injury or damage that happens during the policy period (Section I, 1.b(2)), even if the suit arrives years later; a claims-made policy pays only claims first made while a policy is in force. AIA A101-2017 Exhibit A §A.3.2.2.1 specifies “an occurrence form”, and the Southern California Association of Governments (rev. 07/24/22) asks for cover at least as broad as the occurrence form CG 0001.
The difference matters most after handover. A roof that leaks in year 4 and damages a tenant’s stock triggers the occurrence policy in force in year 4, when the damage happened. Under a claims-made policy, the contractor needs continuous cover, or a purchased extended reporting period, through the date the claim is made.
What is completed operations coverage and how long do you need it?
Completed operations coverage pays for injury or damage that happens after your work is finished, such as a handrail that fails a year after turnover. In CG 00 01 it is the “products-completed operations hazard” (definition 16) with its own aggregate limit. AIA owners ask for proof of it at final payment, and Exhibit A §A.3.2.1 requires the insurance to run through the 1-year correction period.
| Step | Event | Rule | Source |
|---|---|---|---|
| 1 | Before work starts | Certificate of insurance to the owner | Exhibit A §A.3.1.1 |
| 2 | During the work | Exclusions j(5) and j(6) remove damage to the part being worked on; builder’s risk covers the work | CG 00 01, exclusion j |
| 3 | Work deemed completed | Earliest of: all contract work done; all work at the site done; a part put to its intended use by someone other than another contractor or subcontractor on the same project | CG 00 01, definition 16.a(2) |
| 4 | Final payment | New certificate showing completed operations cover, renewed until the required periods end | Exhibit A §A.3.1.1 |
| 5 | Correction period ends | Keep the insurance until the 1-year correction period in A201-2017 §12.2.2 expires | Exhibit A §A.3.2.1 |
| 6 | Florida repose | Defect suits must start within 7 years of the earliest TCO, CO, certificate of completion or abandonment | Fla. Stat. §95.11(3)(b) |
Work that still needs correction or repair but is otherwise complete counts as completed under definition 16. When an owner moves into one floor early, that floor can fall under the completed operations aggregate while the rest is still ongoing work. Our guide to substantial completion explains how that date is set in the contract.
What limits do owners and public agencies require?
The common commercial floor is $1,000,000 per occurrence and $2,000,000 aggregate, with larger jobs adding an umbrella. Caltrans scales limits to the bid: $1,000,000 and $2,000,000 up to a $10,000,000 bid, $2,000,000 and $4,000,000 above it, and a $5,000,000 to $25,000,000 umbrella. Federal contracts on government installations set a lower floor of $500,000 per occurrence.
| Owner or document | Each occurrence | Aggregate | Products-completed operations | Umbrella or excess | Source |
|---|---|---|---|---|---|
| Caltrans, total bid up to $1,000,000 | $1,000,000 | $2,000,000 | $2,000,000 | $5,000,000 | 7-1.06D(2), rev. 08-2025 |
| Caltrans, bid over $1,000,000 to $10,000,000 | $1,000,000 | $2,000,000 | $2,000,000 | $10,000,000 | 7-1.06D(2) |
| Caltrans, bid over $10,000,000 to $25,000,000 | $2,000,000 | $4,000,000 | $2,000,000 | $15,000,000 | 7-1.06D(2) |
| Caltrans, bid over $25,000,000 | $2,000,000 | $4,000,000 | $2,000,000 | $25,000,000 | 7-1.06D(2) |
| Anderson County, Texas, AIA A101 Exhibit A (2026) | $1,000,000 | $2,000,000 | Required, limit not stated separately | Allowed to make up limits (§A.3.2.4) | Exhibit A §A.3.2.2.1 |
| SCAG consultants (rev. 07/24/22) | $1,000,000 | Per project, or twice the occurrence limit | Not stated | Not stated | SCAG insurance requirements |
| Federal contracts on government installations | $500,000 bodily injury | Not stated | Not stated | Not stated | FAR 28.307-2(b)(1) |
Caltrans adds rules that a quote must meet: the general aggregate must apply separately to the contract (footnote b), the policy may not exclude explosion, collapse and underground hazards, and a self-insured retention over $50,000 needs a CPA declaration (section 3-1.07). Small business subcontractors are measured by their subcontract amount, not the prime contractor’s bid. Owners using AIA forms fill the blanks themselves; our AIA A101 guide shows how Exhibit A is completed.
Which states require general liability insurance for a contractor license?
Several states make liability insurance a licensing condition, but the amounts are floors, not project limits. Florida’s 61G4-15.003 asks general contractors for $300,000 of public liability and $50,000 of property damage cover, and Oregon asks a Level 1 commercial general contractor for $2,000,000. Our contractor licensing registry covers all 50 states.
| State | Who | Minimum general liability | Source (checked) |
|---|---|---|---|
| Florida | Certified or registered general and building contractors | $300,000 public liability; $50,000 property damage; certificate holder must be DBPR’s Construction Industry Licensing Board | Fla. Admin. Code R. 61G4-15.003 (2026-11-02) |
| Florida | Residential, plumbing, roofing, mechanical and most specialty contractors | $100,000 public liability; $25,000 property damage | R. 61G4-15.003 (2026-11-02) |
| Oregon | Commercial general contractor Level 1 / Level 2 | $2,000,000 / $1,000,000 aggregate | ORS 701.084, CCB (2026-11-02) |
| Oregon | Residential general contractor | $500,000 per occurrence | Oregon CCB (2026-11-02) |
| Utah | Licensed contractors | $1,000,000 per incident; $2,000,000 total | Utah DOPL (2026-10-04) |
| Georgia | Commercial general contractor | $500,000 per occurrence | Georgia Secretary of State (2026-10-04) |
| Mississippi | Commercial license, jobs over $50,000 | $300,000 per occurrence; $600,000 aggregate | MSBOC FAQ (2026-11-02) |
| Texas | Responsible Master Plumber | $300,000 for all claims in a one-year period | Tex. Occ. Code §1301.552 (2026-11-01) |
| Washington | Registered contractors | $50,000 property damage; $100,000 one person; $200,000 more than one person | RCW 18.27.050 (2026-11-02) |
| Alaska | Registered general contractors | $20,000 property; $50,000 one person; $100,000 more than one person | Form 08-4815, rev. 09/03/2025 (2026-11-02) |
A license-level policy can still fall short of a contract: a Florida contractor carrying the $300,000 floor would need more than three times that per occurrence to meet a $1,000,000 owner requirement. Washington suspends a registration automatically when the policy lapses or is cancelled (RCW 18.27.050(2)).
How much does general liability insurance for contractors cost?
No regulator or public body publishes a price list for contractor general liability, because each insurer files its own rates and prices each firm on its trade, size, limits and claims. Public data shows the direction instead: the BLS producer price index for product and other non-auto liability insurance reached 179.253 in September 2026 (preliminary), 10.0% above September 2025.
| Year (annual average) | Non-auto liability insurance index | Workers’ compensation insurance index |
|---|---|---|
| 2016 | 117.0 | 109.3 |
| 2017 | 116.3 | 106.9 |
| 2018 | 118.6 | 102.8 |
| 2019 | 120.1 | 102.0 |
| 2020 | 123.4 | 99.4 |
| 2021 | 125.192 | 93.418 |
| 2022 | 125.934 | 89.487 |
| 2023 | 130.292 | 89.394 |
| 2024 | 141.337 | 86.212 |
| 2025 | 155.571 | 84.468 |
Both series are BLS producer price indexes for direct property and casualty insurers, June 1998 = 100 (PCU524126524126403 and PCU5241265241266, accessed November 2, 2026). The liability index rose 33.0% from 2016 to 2025 while the workers’ compensation index fell 22.7%, so a contractor’s liability premium and comp premium can move in opposite directions at renewal. Our workers comp rates by state page covers the comp side.
What did contractor liability insurance cost on public projects?
The most specific public figures we found come from Caltrans, which removed contractors’ insurance from bids on three owner-controlled insurance program (OCIP) projects and reported the credits. Contractors’ general liability, workers’ compensation and excess premiums equalled 0.40% to 1.71% of project value, before a 10% to 15% markup (Caltrans report to the Legislature, April 2009).
| Caltrans contract | Project value | Contractor insurance credit | Credit as % of value |
|---|---|---|---|
| 03-3338U4, State Route 65 Lincoln Bypass | $137,000,000 | $1,102,758 | 0.80% |
| 07-166824, Interstate 10 HOV lanes | $15,500,000 | $265,574 | 1.71% |
| 04-253794, Interstate 680 | $37,000,000 | $148,884 | 0.40% |
| Total | $189,500,000 | $1,517,216 | 0.80% |
These are 2009 figures for heavy highway work, they combine three lines of cover, and Caltrans called the credits incomplete. Applied to a $10,000,000 project, the range works out to $40,000 at 0.40% and $171,000 at 1.71% (CB&C arithmetic). Caltrans’ 2007 report says OCIP administrators price this cost from each contractor’s “declaration pages and rating sheets” and the state experience modifier (Caltrans, January 2007).
What moves a contractor’s general liability premium?
Five public signals move the price: the limits the contract demands, the liability insurance market, the trade, the contractor’s loss record and the retention it keeps. Caltrans alone moves the umbrella from $5,000,000 to $25,000,000 by bid size, and the BLS liability index added 10.0% in the year to September 2026.
| Driver | Direction | Evidence |
|---|---|---|
| Higher limits or an added umbrella | Up | Caltrans tiers move from $1,000,000 to $2,000,000 per occurrence and from $5,000,000 to $25,000,000 umbrella with bid size |
| Market pricing for liability lines | Up 10.0% in the 12 months to Sept 2026 | BLS PPI PCU524126524126403 |
| Trade and building type | Up for roofing, residential, EIFS, below-grade work | Insurers add exclusions for these; Exhibit A §A.3.2.2.2.7 to .11 lists them |
| Claims history | Up after losses | Caltrans OCIP pricing uses each contractor’s experience modifier (2007 report) |
| Deductible or self-insured retention | Down as the retention rises | Caltrans requires a CPA declaration for retentions over $50,000 (3-1.07) |
| Project-specific aggregate | Up | Caltrans footnote b and SCAG require the aggregate to apply per project |
How does CGL fit with builder’s risk, workers’ comp and additional insured status?
Each policy answers a different claim. General liability pays injury and damage to other people and their property. Builder’s risk pays for damage to the building under construction, which CGL exclusions j(5) and j(6) leave out. Workers’ compensation pays your own employees (exclusions d and e). Commercial auto pays vehicle claims (exclusion g), and Caltrans asks for $5,000,000 or more of umbrella above all of it.
- Start with the injury or damage on or from the job.
- Is the injured person your own employee? Yes: workers’ compensation and employer’s liability (CGL exclusions d and e).
- No: was an auto you own, rent or operate involved? Yes: commercial auto policy (CGL exclusion g).
- No: is the damaged property the work itself, before completion? Yes: builder’s risk on the project (CGL exclusions j(5) and j(6)).
- No: is the claim only the cost to fix your own completed work? Yes: excluded, unless a subcontractor did the work (CGL exclusion l).
- No: CGL Coverage A, third-party bodily injury or property damage plus defense, paid up to the each occurrence limit inside the general or completed operations aggregate.
| Policy | Protects | Pays for | Who usually buys | Source |
|---|---|---|---|---|
| Commercial general liability | Contractor, plus additional insureds | Third-party injury and property damage, personal and advertising injury, defense | Contractor | CG 00 01 04 13 |
| Builder’s risk | Owner and contractor | Physical loss to the work, materials and temporary works | Owner under AIA Exhibit A §A.2.3.1 unless shifted | Exhibit A §A.2.3.1 |
| Workers’ compensation | Employees | Statutory benefits for job injuries | Each employer | Exhibit A §A.3.2.5 |
| Commercial auto | Contractor | Vehicle bodily injury and property damage | Contractor; $1,000,000 per accident in Anderson County’s Exhibit A | Exhibit A §A.3.2.3 |
| Umbrella or excess | Contractor and additional insureds | Claims above the CGL and auto limits | Contractor; $5,000,000 to $25,000,000 on Caltrans work | 7-1.06D(2) |
| Performance and payment bonds | Owner, subcontractors, suppliers | Contractor default and unpaid bills; not insurance for the contractor | Contractor, 100% of contract in Anderson County | Exhibit A §A.3.4 |
Our builder's risk insurance guide covers the property side clause by clause.
Owners also want to be on the contractor’s policy. Exhibit A §A.3.1.3 asks for the owner, architect and consultants as additional insureds on ISO endorsements CG 20 10 07 04 (ongoing operations) and CG 20 37 07 04 (completed operations), primary and non-contributory. Bonds are a separate guarantee, covered in our construction surety bond statistics.
What should you check before you sign or bid?
Match the policy to the contract, not the license: a $300,000 Florida license policy does not meet a $1,000,000 owner requirement. Read the owner’s insurance exhibit for the per-occurrence limit, the aggregate basis, the completed operations period and any banned exclusions, then compare the declarations page and endorsement schedule line by line. This page is general information, not insurance or legal advice; ask your broker in writing whether each listed exclusion appears on your policy.
| If | Then | Rule |
|---|---|---|
| You bid a Caltrans job up to $10,000,000 | Carry $1,000,000 per occurrence, $2,000,000 aggregate and a $5,000,000 or $10,000,000 umbrella | 7-1.06D(2) |
| You bid a Caltrans job over $10,000,000 | Carry $2,000,000 per occurrence, $4,000,000 aggregate and a $15,000,000 or $25,000,000 umbrella | 7-1.06D(2) |
| You work on a federal installation | At least $500,000 bodily injury per occurrence; the contract may ask for more | FAR 28.307-2(b)(1) |
| The contract is AIA A101 with Exhibit A | Occurrence form; limits as filled in (Anderson County: $1,000,000 / $2,000,000); keep cover through the 1-year correction period | §A.3.2.1, §A.3.2.2.1 |
| Your policy has a roofing, residential, EIFS or subsidence exclusion and the job involves it | Exhibit A forbids it; get the endorsement removed before signing | §A.3.2.2.2.7 to .10 |
| Subcontractors perform most of the work | Confirm exclusion l still carves out subcontractor work | CG 00 01, exclusion l |
| Your insurer offers a claims-made form | Most construction owners require the occurrence form | §A.3.2.2.1; SCAG |
| You hold a Florida general contractor license | File a certificate showing $300,000 / $50,000 with DBPR’s licensing board as holder | R. 61G4-15.003 |
| The owner will occupy part of the building early | That part may be “completed” for CGL; tell the builder’s risk insurer too | CG 00 01, definition 16 |
Owners checking a contractor can use the same 9 rows in reverse. Our guide on how to choose a commercial contractor lists the certificate checks, and how we vet builders explains what CB&C reads on a certificate.
Where do common guides differ from the policy form?
Several ranking guides state costs or coverage rules without a primary source. The table sets 4 of those claims, from guides dated 2022 to 2026, against the ISO form, the BLS index and state rules, so a reader can check each one. We describe the guides without naming them.
| What a guide says | What the primary source says |
|---|---|
| A top-ranking broker article (2022) says general contractors pay “$825 to $1,090 per year” | No source, limit, trade or date is given, and no regulator publishes such a figure. The BLS liability insurance index rose 10.0% in the year to September 2026, so a 2022 figure is dated. |
| The same article lists libel and false arrest under bodily injury | CG 00 01 04 13 places them under Coverage B, personal and advertising injury (definition 14), with its own limit. |
| Guides say general liability “does not cover faulty workmanship” | Exclusions j(6) and l remove repair of your own work, but exclusion l does not apply to work a subcontractor performed, and damage to other property can be Coverage A property damage. |
| A 2026 overview says “many states” require it, naming none | Florida, Oregon, Utah, Georgia, Mississippi, Washington and Alaska set dollar minimums in rules or board pages (state table above). |
Owners are added to the contractor’s policy by endorsement, as explained in our additional insured guide, and performance risk is covered separately by the bonds in our performance bond guide.
How we compiled this
We read 19 primary documents in October and November 2026: the ISO CG 00 01 04 13 form, Caltrans insurance specifications and two Caltrans reports to the Legislature, FAR 28.307-2, an AIA A101-2017 Exhibit A filled in by a Texas county, a regional agency’s insurance requirements, state licensing rules for 8 states and two BLS price index series. We excluded insurer and broker premium averages because none states a method, limit or date.
Frequently asked questions
Is general liability insurance required by law for contractors?
Not by one national law, but many states tie it to the license. Florida requires $300,000 of public liability and $50,000 of property damage cover for general contractors under Rule 61G4-15.003, Mississippi requires $300,000 per occurrence for commercial licenses, and Washington suspends a registration when the policy lapses. Owners and public agencies then require higher limits by contract.
How much general liability insurance does a contractor need?
Most commercial contracts ask for $1,000,000 per occurrence and $2,000,000 aggregate. Caltrans keeps those limits for bids up to $10,000,000 and raises them to $2,000,000 and $4,000,000 above that, plus an umbrella of $5,000,000 to $25,000,000. Federal contracts on government installations set a $500,000 per occurrence bodily injury floor under FAR 28.307-2.
Does a contractor's general liability policy cover subcontractors?
Not as insureds by default; subcontractors need their own policies and certificates. The contractor’s CG 00 01 policy can still respond to claims arising from a subcontractor’s work, and exclusion l does not remove damage to completed work that a subcontractor performed. AIA Exhibit A §A.3.2.2.2 bars endorsements that delete that subcontractor exception.
Does general liability cover damage to the building I am working on?
Mostly not while the work is underway. Exclusion j(5) of CG 00 01 removes damage to the particular part of real property you or your subcontractors are working on, and j(6) removes repair of work done incorrectly. That property gap is what builder’s risk insurance covers, which the owner usually buys under AIA A101-2017 Exhibit A §A.2.3.1.
What is the difference between general liability and workers' compensation for contractors?
General liability pays claims by people outside your company, such as a passer-by or the owner’s tenant. Workers’ compensation pays your own employees’ job injuries, which CG 00 01 exclusions d and e remove from general liability. BLS price indexes moved in opposite directions: liability rose 33.0% from 2016 to 2025 while workers’ compensation fell 22.7%.
Are defense costs included in the general liability limit?
Not on the standard occurrence form. Under the Supplementary Payments clause of CG 00 01 04 13, defense expenses, court costs, post-judgment interest and up to $250 a day of the insured’s lost earnings “will not reduce the limits of insurance”. Check the declarations: some non-standard policies put defense inside the limit.
Sources
- Insurance Services Office: Commercial General Liability Coverage Form CG 00 01 04 13 (ISO form, reference copy) (accessed 2026-11-02)
- California Department of Transportation, Division of Construction: Insurance Requirements, Standard Specifications 3-1.07 and 7-1.06D (revised 08-2025) (accessed 2026-11-02)
- Acquisition.gov (GSA): FAR 28.307-2 Liability (FAC 2026-01, effective 03/13/2026) (accessed 2026-11-02)
- Anderson County, Texas: AIA A101-2017 Exhibit A, Insurance and Bonds, AgriLife facility (produced 04/16/2026) (accessed 2026-11-02)
- Southern California Association of Governments: Insurance Requirements (rev. 07/24/22) (accessed 2026-11-02)
- Florida Construction Industry Licensing Board: Rule 61G4-15.003, Public Liability and Property Damage Insurance (accessed 2026-11-02)
- Oregon Revised Statutes (oregon.public.law): ORS 701.084, Commercial contractor insurance (accessed 2026-11-02)
- Oregon Construction Contractors Board: CCB License: endorsements and insurance amounts (accessed 2026-11-02)
- Washington State Legislature: RCW 18.27.050, Insurance or financial responsibility (accessed 2026-11-02)
- Alaska Department of Commerce, Community, and Economic Development: General Contractor Registration Application, form 08-4815 (rev. 09/03/2025) (accessed 2026-11-02)
- Mississippi State Board of Contractors: Frequently Asked Questions (accessed 2026-11-02)
- Georgia Secretary of State: Residential and Commercial General Contractors FAQ (accessed 2026-10-04)
- Utah Division of Professional Licensing: Specialty Contractor License (accessed 2026-10-04)
- Texas Legislature: Occupations Code Chapter 1301, Plumbers (§1301.552) (accessed 2026-11-01)
- U.S. Bureau of Labor Statistics: PPI: Direct property and casualty insurers, product and other non-auto liability insurance (PCU524126524126403) (accessed 2026-11-02)
- U.S. Bureau of Labor Statistics: PPI: Direct property and casualty insurers, workers’ compensation insurance (PCU5241265241266) (accessed 2026-11-02)
- California Department of Transportation: Owner Controlled Insurance Program Status Report, Report to the Legislature (April 2009) (accessed 2026-11-02)
- California Department of Transportation: Owner Controlled Insurance Program, Report to the Legislature (January 2007) (accessed 2026-11-02)
- The Florida Senate: Florida Statutes §95.11 (2025) (accessed 2026-11-02)