A commercial construction loan funds a new building in monthly draws, then a permanent mortgage repays it. Federal guidelines cap bank construction loans at 80% of appraised value; SBA 504 can cut the owner’s share to 10%.
Key takeaways
- Banks follow an 80% loan-to-value guideline for commercial construction loans, measured on appraised value, under 12 CFR Part 365, Appendix A; raw land is 65% and land development 75%.
- For a building repaid from rents or a sale, a bank avoids a 150% risk weight only if the borrower puts in at least 15% of the as-completed value before the first advance (HVCRE definition, 12 CFR 324.2).
- SBA 504 lets an owner-occupant contribute 10% of project cost, 15% for a business 2 years old or less or a special-purpose building, and 20% for both (13 CFR 120.910); the standard debenture cap is $5,000,000 (13 CFR 120.931).
- SBA 7(a) loans top out at $5,000,000, with a variable rate capped at prime plus 3.0 points above $350,000: 10.00% at the 7.00% prime rate of October 29, 2026 (13 CFR 120.214; Federal Reserve H.15).
- In our worked budget for a 20,000 sq ft Dallas office costing $5,689,000, a $5,500,000 appraisal caps a bank loan at $4,400,000, so the owner funds $1,289,000, or 22.7% of cost.
How does a commercial construction loan work?
A commercial construction loan is short-term debt to build or substantially renovate a commercial property. The lender commits a maximum at closing, the owner spends its equity first, and the lender then advances money against inspected work, charging interest only on the drawn balance. The SBA SOP 50 10 8.1 (effective October 1, 2026) writes the equity-first rule into every SBA construction loan.
- Underwrite and appraise. The lender reviews plans, a fixed-price contract and the budget, and orders an as-completed appraisal; for an FDIC-supervised bank, a commercial real estate loan above $500,000 needs a state certified appraiser (12 CFR 323.3).
- Close, owner cash first. The loan is sized near 80% of value or less, and the owner’s cash and land go into the project before the first loan dollar (12 CFR Part 365; SBA SOP 50 10 8.1).
- Monthly draws. The contractor submits a pay application, an inspector confirms work in place, lien waivers come in, and the lender funds only actual outlays.
- Interest on the drawn balance. Payments are interest-only at a floating rate (prime was 7.00% on October 29, 2026) and are usually paid from an interest reserve inside the loan.
- Completion. Final inspection against the plans, final lien waivers, a certificate of occupancy, and retainage released to the contractor.
- Takeout. A permanent mortgage, a conversion to a term loan under the same note, or an SBA 504 debenture repays the interim lender.
The 9 numbers below recur through every step. Each comes from a regulation, an SBA rule or the Federal Reserve’s October 30, 2026 H.15 release, not a lender quote.
| Number | What it governs | Source |
|---|---|---|
| 80% | Maximum loan-to-value for commercial, multifamily and other nonresidential construction loans | 12 CFR 365, App. A |
| 65% / 75% | Raw land / land development loan-to-value limits | 12 CFR 365, App. A |
| 15% | Borrower capital, as a share of as-completed value, that keeps an income-producing project out of HVCRE | 12 CFR 324.2 |
| 150% | Bank risk weight on an HVCRE loan | 12 CFR 324.32(j) |
| $500,000 | Commercial real estate loan size above which an FDIC-supervised bank needs a state certified appraiser | 12 CFR 323.3(d)(2) |
| $350,000 | SBA 7(a) construction component above which 100% performance and payment bonds are required | SBA SOP 50 10 8.1 |
| $5,000,000 | SBA 7(a) loan cap; standard SBA 504 debenture cap | 13 CFR 120.151, 120.931 |
| $10,000,000 | Combined 7(a) plus 504 limit from July 4, 2026, when the 7(a) loan comes first | SBA, May 18, 2026 |
| 7.00% / 3.94% | Bank prime rate / SOFR on October 29, 2026 | Fed H.15; New York Fed |
How much can you borrow: loan-to-value or loan-to-cost?
Two ratios set the ceiling, and the lower one wins. Loan-to-value (LTV) divides the loan by the appraised value of the finished building; federal guidelines in 12 CFR Part 365 tell banks to keep commercial construction loans at or below 80% LTV. Loan-to-cost (LTC) divides the loan by the total budget. No regulation fixes LTC, so each lender sets its own limit.
The value in that test is the as-completed value, not the land value today. SBA SOP 50 10 8.1 requires the appraisal for new construction to estimate market value upon completion, and the lender must later get a statement that the building matches the plans the appraiser relied on. When the appraisal lands below cost, the 80% LTV test binds and the owner covers the gap.
| Loan category | Supervisory LTV limit | Source |
|---|---|---|
| Raw land | 65% | 12 CFR 365, App. A |
| Land development | 75% | 12 CFR 365, App. A |
| Construction: commercial, multifamily and other nonresidential | 80% | 12 CFR 365, App. A |
| Construction: 1 to 4 family residential | 85% | 12 CFR 365, App. A |
| Improved property (completed building) | 85% | 12 CFR 365, App. A |
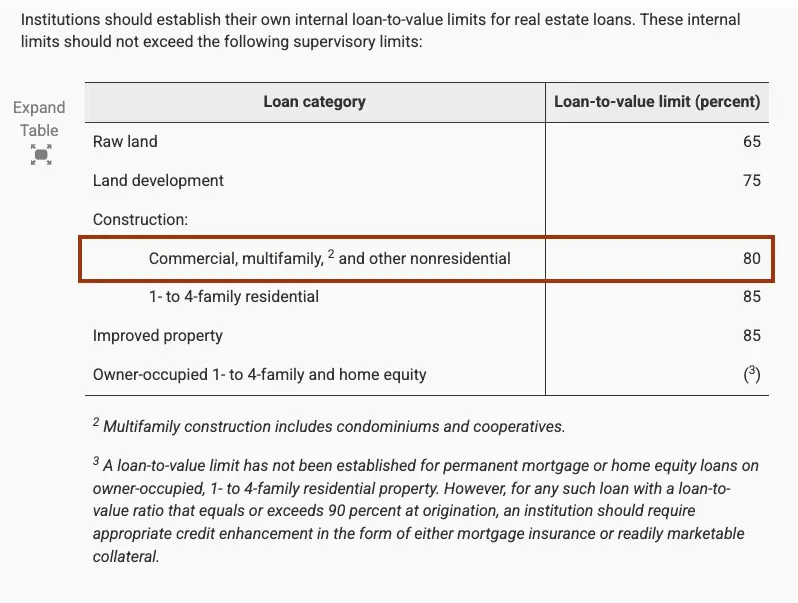
Three lines in the same appendix shape a construction loan. A loan that funds land development and then the building takes the limit of the final phase, 80%, and “loan disbursements should not exceed actual development or construction outlays”. Banks may exceed the limits case by case, but all such loans together should stay under 100% of total capital, and the commercial share under 30%.
The appendix also lists excluded transactions: a loan guaranteed by a U.S. government agency is outside the limit if the guaranty at least equals the slice above 80%. That is why an SBA 7(a) loan, with a guaranty of up to $3,750,000 on a $5,000,000 loan, can lend past 80% of value. For current hard-cost ranges by building type, our guide to commercial construction cost per square foot compiles the RLB and BLS figures.
How much equity do you need, and when does it go in?
Plan on equity at least equal to the gap between total cost and the loan, paid in before the lender’s first dollar. On a bank loan for an income-producing project, the HVCRE rule makes 15% of as-completed value the practical floor. SBA 504 sets 10%, 15% or 20% of project cost, and SBA 7(a) requires 10% only from start-ups operating 1 year or less.
| Path | Minimum owner money | What counts | Source |
|---|---|---|---|
| Bank loan, building repaid from rents or sale | 15% of as-completed appraised value, in before the bank advances funds and kept in until completion and stable cash flow | Cash, unencumbered readily marketable assets, paid development costs, contributed land at appraised value | 12 CFR 324.2 (HVCRE) |
| Bank loan, owner-occupied building repaid from business cash flow | No federal number; each bank’s policy must set minimum initial investment and hard equity | Bank policy | 12 CFR 365, App. A |
| SBA 504, existing business, general-purpose building | 10% of project cost | Cash, or land that is part of the project | 13 CFR 120.910 |
| SBA 504, business 2 years old or less, or limited or single-purpose building | 15% of project cost | Same | 13 CFR 120.910 |
| SBA 504, both conditions | 20% of project cost | Same | 13 CFR 120.910 |
| SBA 7(a), start-up operating 1 year or less | 10% of total project cost | Cash and other sources listed in the SOP | SBA SOP 50 10 8.1 |
| SBA 7(a), established business | Lender judgment; the credit memo must discuss equity | Lender policy | SBA SOP 50 10 8.1 |
Land you already own usually counts, but its value depends on when you bought it. For SBA 504, land bought less than 2 years before the application counts at cost; land held 2 years or more counts at appraised fair market value (SBA SOP 50 10 8.1). Under the HVCRE rule, contributed real property counts at its appraised value.
What does a commercial construction loan cost in November 2026?
No federal agency publishes an average commercial construction loan rate, so start from the index your lender quotes. On October 29, 2026 the bank prime rate was 7.00% and SOFR was 3.94%; lenders add a spread set deal by deal. SBA 7(a) caps that spread, and SBA 504 debenture rates follow the 10-year Treasury, which closed at 4.98%.
| Benchmark | Rate | Date | Where it shows up | Source |
|---|---|---|---|---|
| Bank prime loan rate | 7.00% | Oct 29, 2026 | Floating bank construction loans; SBA 7(a) base rate | Fed H.15, Oct 30, 2026 |
| SOFR (overnight) | 3.94% | Oct 29, 2026 | Floating rate on larger bank loans | New York Fed |
| 10-year Treasury | 4.98% | Oct 29, 2026 | SBA 504 debenture rate is pegged to it | Fed H.15; SBA 504 page |
| Federal funds, effective | 3.88% | Oct 29, 2026 | Policy rate behind prime | Fed H.15 |
| 7(a) cap, loans over $350,000 | Prime + 3.0 = 10.00% | Oct 29, 2026 prime | Maximum variable rate | 13 CFR 120.214(d) |
| 7(a) cap, $250,001 to $350,000 | Prime + 4.5 = 11.50% | Oct 29, 2026 prime | Maximum variable rate | 13 CFR 120.214(d) |
| 7(a) cap, $50,001 to $250,000 | Prime + 6.0 = 13.00% | Oct 29, 2026 prime | Maximum variable rate | 13 CFR 120.214(d) |
Credit is available but not growing. Banks held $453.5 billion of construction and land development loans on June 30, 2026, and 0.99% were noncurrent (FDIC Quarterly Banking Profile, Q2 2026). In the July 2026 Senior Loan Officer Opinion Survey, standards for construction and land development loans “remained basically unchanged on net”, while a moderate net share of banks saw weaker demand. Our construction lending tracker follows these series every quarter.
Fees add to the rate. On a $5,000,000 SBA 7(a) loan with a 75% guaranty, the maximum upfront guaranty fee is $138,125, and it can be financed (SBA SOP 50 10 8.1). SBA puts total 504 fees at about 3% of the debenture, also financeable. Bank origination fees are not reported to regulators, so get them in writing on the term sheet.
Worked example: what does a $5.7 million owner-occupied office need?
Here is one owner-occupied project run through the three tests with every input shown. The building is a 20,000 sq ft office in Dallas; hard cost uses $200 per sq ft, inside the $165 to $240 range for Dallas secondary offices in the Rider Levett Bucknall (RLB) Q3 2026 cost report. Inputs marked as assumptions are ours; swap in your own.
| Budget line | Amount | Basis |
|---|---|---|
| Land, paid in cash by the owner | $800,000 | Assumption |
| Hard cost, 20,000 sq ft at $200 | $4,000,000 | RLB Q3 2026: Dallas secondary office $165 to $240 per sq ft |
| Construction contingency, 7% of hard cost | $280,000 | GSA P120 (PBS 1000.6B): 7% at award for new construction |
| Soft costs: design, permits, legal, title, appraisal, builder’s risk | $400,000 | Assumption: 10% of hard cost |
| Lender fee, 1% of the loan | $44,000 | Assumption |
| Interest reserve | $165,000 | $4,400,000 x 50% average balance x 7.50% x 12 months |
| Total project cost | $5,689,000 | Sum |
| Test | Arithmetic | Result |
|---|---|---|
| 80% LTV guideline | 80% x $5,500,000 as-completed appraisal (assumption) | Loan up to $4,400,000 |
| Loan-to-cost | $4,400,000 / $5,689,000 | 77.3% |
| Owner money | $5,689,000 minus $4,400,000 | $1,289,000, or 22.7% of cost |
| HVCRE floor (only if leased out or sold) | 15% x $5,500,000 | $825,000, met |
| Interest rate used | Prime 7.00% + 0.50 spread (assumption) | 7.50% |
The appraisal moves the owner’s cash more than the rate does. In the runs below, a $500,000 lower appraisal adds $381,000 of owner money, while a 1-point higher rate adds $22,000 through the reserve.
| Change from the base case | Loan | Total cost | Owner money |
|---|---|---|---|
| Base case | $4,400,000 | $5,689,000 | $1,289,000 |
| Appraisal $5,000,000 | $4,000,000 | $5,670,000 | $1,670,000 |
| Appraisal $6,000,000 | $4,800,000 | $5,708,000 | $908,000 (HVCRE floor $900,000) |
| Build takes 18 months | $4,400,000 | $5,771,500 | $1,371,500 |
| Rate 8.50% | $4,400,000 | $5,711,000 | $1,311,000 |
| Rate 10.00% (7(a) cap level) | $4,400,000 | $5,744,000 | $1,344,000 |
How do draws, inspections and the interest reserve work?
Draws pay the contractor for work in place, usually once a month. The lender funds a draw only after a pay application, an inspection that confirms the work, and lien waivers for the prior payment; 12 CFR Part 365 says disbursements should not exceed actual construction outlays. Interest accrues only on what has been drawn, and an interest reserve inside the loan pays it.
- Pay application. The contractor bills percent complete against the schedule of values on an AIA G702 and G703; our AIA G702 payment application guide shows the form line by line.
- Inspection. The lender’s inspector checks work in place. When a CDC provides interim financing on a 504 project, a qualified engineer, appraiser or other party must inspect before every progress payment (SBA SOP 50 10 8.1).
- Lien waivers and title. Waivers from the contractor, subcontractors and suppliers for amounts already paid; SBA lenders must collect them from all of these parties and document them in the loan file.
- Balance check. Undrawn loan plus remaining owner money must cover cost to complete. SBA lenders must see the borrower’s ability to pay overruns before approving a contract change, and neither the lender nor SBA must raise the loan.
- Funding. Money goes to the contractor or a title company, minus retainage under the contract.
- Interest. The month’s interest is charged on the drawn balance and paid from the interest reserve.
Tie the pay application to a clean schedule of values and collect conditional and unconditional lien waivers with each draw, because SBA SOP 50 10 8.1 makes SBA lenders collect waivers from every contractor, subcontractor and supplier; our pages on the schedule of values and lien waivers cover both forms.
The interest reserve is sized as loan x average share drawn x rate x months. With even draws the average balance is about half the loan, so a $4,400,000 loan at 7.50% for 12 months needs $165,000. 12 CFR Part 365 tells banks to set standards and limits on interest reserves, and lenders size them to the schedule, so a late finish can exhaust the reserve before the takeout.
| Rate | Reserve, 12-month build | Reserve, 18-month build |
|---|---|---|
| 6.50% | $143,000 | $214,500 |
| 7.50% | $165,000 | $247,500 |
| 8.50% | $187,000 | $280,500 |
| 10.00% (7(a) cap over $350,000) | $220,000 | $330,000 |
What will the lender require from you and your contractor?
Expect the lender to underwrite the contractor as closely as the owner. SBA rules spell this out: a fixed-price contract with a licensed contractor, final plans, and, when the 7(a) construction component tops $350,000, 100% performance and payment bonds plus builder’s risk and workers’ compensation insurance, unless the lender hires third-party construction monitoring with funds control.
| Requirement | When it applies | Source |
|---|---|---|
| Fixed-price construction contract with a licensed contractor; no material plan changes without lender (and surety) consent | SBA 7(a) and 504 construction | SBA SOP 50 10 8.1 |
| 100% performance bond and labor and materials payment bond from a Treasury-approved surety; builder’s risk and workers’ comp | 7(a) construction component over $350,000, unless the lender uses third-party construction management with funds control | SBA SOP 50 10 8.1; 13 CFR 120.200 |
| Evidence the building meets NEHRP seismic provisions (ASCE 7 or the International Building Code) | New building or addition, SBA loans | SBA SOP 50 10 8.1; 13 CFR 120.174 |
| Environmental investigation, report dated within 1 year of the SBA loan number | All commercial property taken as SBA collateral | SBA SOP 50 10 8.1 |
| Hazard insurance on collateral | SBA loans over $500,000 | 13 CFR 120.160(c) |
| As-completed appraisal by a state certified appraiser | Commercial real estate loans over $500,000 at FDIC-supervised banks | 12 CFR 323.3 |
| Projections showing debt service coverage of 1.15 or more within 2 years of the end of construction | SBA start-ups and loans based on projections | SBA SOP 50 10 8.1 |
Bonds and builder’s risk insurance are priced into the contract, so ask bidders to carry them as separate lines; on SBA 7(a) jobs with more than $350,000 of construction, both are mandatory. Our pages on construction surety bonds, builder’s risk insurance and the Phase I environmental site assessment explain what each costs and covers.
Bank loan, SBA 504 or SBA 7(a): which fits your project?
A conventional bank loan fits investor buildings and owner projects with strong equity. SBA 504 fits owner-occupants who want a long fixed rate and the smallest contribution, if the business will occupy at least 60% of a new building. SBA 7(a) fits owner-occupants who want one lender and one loan up to $5,000,000, at a capped floating rate.
| Feature | Conventional bank loan | SBA 504 | SBA 7(a) | Source |
|---|---|---|---|---|
| Maximum | Bank policy within the 80% LTV guideline | Debenture $5,000,000 ($5,500,000 for small manufacturers and energy projects), plus a bank loan at least as large | $5,000,000 loan | 12 CFR 365; 13 CFR 120.931, 120.920, 120.151 |
| Owner money | Bank policy; 15% of value if HVCRE | 10%, 15% or 20% of project cost | 10% for start-ups; else lender judgment | 12 CFR 324.2; 13 CFR 120.910; SOP 50 10 8.1 |
| Rate | Spread over prime or SOFR | Debenture fixed, pegged to the 10-year Treasury; bank piece negotiated | Variable cap prime + 3.0 above $350,000 | SBA 504 page; 13 CFR 120.214 |
| Term after completion | Set by lender | 10, 20 or 25 years | Up to 25 years plus the construction period | SBA 504 page; 13 CFR 120.212 |
| Who funds the build | Same bank | Interim lender; debenture sold after completion repays it | The 7(a) lender | SOP 50 10 8.1 |
| Occupancy | None | 60% of a new building | 60% of a new building | 13 CFR 120.131 |
Run the same $5,689,000 budget through each path. The bank loan needs $1,289,000 of owner money. Under SBA 504, the bank lends 50% ($2,844,500), the CDC 40% ($2,275,600) and the owner 10% ($568,900), which the $800,000 of land already covers; the bank’s first lien is 51.7% of value, and 504 fees of about 3% add roughly $68,000 to the debenture. Under 7(a), a $5,000,000 loan leaves $855,625 of owner money after the $138,125 maximum guaranty fee and a larger reserve.
For how many contractors and owners use each program by state, see our report on SBA loans for construction companies.
Which path should you take? A decision table
Match the project to the first row that fits. Each threshold comes from a regulation or SBA rule, so it holds no matter which lender you call; pricing, fees and covenants still differ by lender, so compare 2 or 3 term sheets.
| If | Then | Rule |
|---|---|---|
| You will lease the building to others or sell it | Use a conventional construction loan; put 15% of as-completed value in cash or land before the first advance | 12 CFR 324.2; SBA 504 excludes rental real estate investment |
| Your business will occupy at least 60% of a new building and the project is about $12.5 million or less | Price SBA 504 (a $5,000,000 debenture at 40% of cost) | 13 CFR 120.131, 120.931 |
| Your business is 2 years old or less | Budget 15% for 504 (20% if the building is special purpose) | 13 CFR 120.910 |
| Your business is 1 year old or less and you want 7(a) | Budget at least 10% of total project cost | SBA SOP 50 10 8.1 |
| The appraisal comes in below cost | Owner money equals cost minus 80% of value at a bank; a 7(a) guaranty can cover the slice above 80% | 12 CFR 365, App. A |
| The 7(a) construction component is over $350,000 | Require 100% performance and payment bonds from the contractor, or confirm the lender uses funds control | SBA SOP 50 10 8.1 |
| SBA financing needed tops $10,000,000 | Use a conventional loan or add one alongside SBA | SBA, May 18, 2026 |
CB&C is a matching service, not a lender. This page is general information, not financial, legal or lending advice; loan terms depend on the borrower, the project and the lender, and SBA rules change with each SOP version; this page reflects SOP 50 10 8.1, effective October 1, 2026.
What do several guides get wrong about commercial construction loans?
Four claims repeat across ranking guides and do not match the primary rules. The most common is a $5.5 million SBA 504 cap for every project; the $5,500,000 figure applies only to small manufacturers and energy projects under 13 CFR 120.931.
| Claim in a top-ranking guide (2026) | What the primary source says | Source |
|---|---|---|
| The SBA 504 loan goes up to $5.5 million | $5,000,000 standard debenture limit; $5,500,000 only for small manufacturers and energy projects | 13 CFR 120.931; SOP 50 10 8.1 |
| SBA 504 needs 10% down | 10% is the floor; 15% for a business 2 years old or less or a special-purpose building, 20% for both | 13 CFR 120.910 |
| SBA 7(a) needs 10% to 20% down | The 10% minimum is for start-ups operating 1 year or less; for others the lender decides | SBA SOP 50 10 8.1 |
| Lenders lend 80% to 85% of cost (no source given) | No rule sets loan-to-cost; the federal guideline is 80% of appraised value, and draws should not exceed actual outlays | 12 CFR 365, App. A |
What happens when construction ends?
Completion triggers the takeout. A bank loan either converts to a term loan under a conversion clause or is refinanced by a permanent mortgage; SBA 7(a) simply begins amortizing over up to 25 years. On a 504 project, the interim lender must be fully disbursed and the project complete before the debenture is sold to repay it (SBA SOP 50 10 8.1).
The lender will want proof of completion: a final inspection, final lien waivers, the certificate of occupancy and a statement that the building matches the appraised plans. For an income-producing project, a bank can move the loan out of HVCRE only after substantial completion and once cash flow covers debt service (12 CFR 324.2). Our substantial completion guide explains the certificate that starts these clocks.
Lenders review the contingency line closely, and our construction contingency guide shows the percentages public owners budget.
For the 504 rules themselves, including FY2027 fees, occupancy tests and a worked $4,000,000 example, see our guide to the SBA 504 loan.
How we compiled this
We read 4 ranking guides for the questions owners ask, then checked every rule against 11 primary documents accessed November 1, 2026: 12 CFR Parts 323, 324 and 365; 13 CFR Part 120; SBA SOP 50 10 8.1; two SBA program pages and SBA’s May 18, 2026 release; the Federal Reserve H.15 release of October 30, 2026; New York Fed SOFR; and RLB’s Q3 2026 cost report. Lender rate quotes were excluded because they are not dated primary data. The worked budget uses labelled assumptions and is arithmetic, not a loan offer.
Frequently asked questions
How much down payment do you need for a commercial construction loan?
At a bank, plan on cost minus 80% of the as-completed appraisal, since 12 CFR Part 365 caps commercial construction loans at 80% of value; for a rental or for-sale building, the HVCRE rule makes 15% of value the floor. SBA 504 requires 10% of project cost, 15% for a business 2 years old or less or a special-purpose building, and 20% for both.
What is the interest rate on a commercial construction loan today?
No agency publishes an average. Floating loans price as a spread over an index: on October 29, 2026 the bank prime rate was 7.00% and SOFR 3.94% (Federal Reserve H.15; New York Fed). SBA 7(a) loans over $350,000 are capped at prime plus 3.0, or 10.00%, and SBA 504 debentures track the 10-year Treasury, then 4.98%.
Can you use an SBA loan for ground-up construction?
Yes, if your business will occupy at least 60% of the new building and may lease up to 20% long term (13 CFR 120.131). SBA 504 covers buildings and land with a debenture up to $5,000,000, and 7(a) lends up to $5,000,000. Investment in rental real estate is not eligible for 504, so pure investor projects need a conventional loan.
Is a commercial construction loan interest-only?
During construction, usually yes: interest is charged only on the amount drawn, and many loans pay it from an interest reserve built into the budget. In our worked example, a $4,400,000 loan at 7.50% with even draws over 12 months needs a $165,000 reserve. Principal payments start at conversion or under the permanent loan.
Can land you already own count as equity?
Usually. Under SBA SOP 50 10 8.1, land bought less than 2 years before a 504 application counts at its cost, and land held 2 years or more counts at appraised fair market value. For bank loans on income-producing projects, the HVCRE rule in 12 CFR 324.2 counts contributed real property at its appraised value toward the 15% capital test.
Does the lender need a performance bond from my contractor?
For an SBA 7(a) loan whose construction component exceeds $350,000, yes: SBA SOP 50 10 8.1 requires 100% performance and payment bonds plus builder’s risk and workers’ compensation insurance, unless the lender uses third-party construction management with funds control. Below $350,000, or on conventional loans, the requirement is set by the lender’s own policy.
What happens to a construction loan when the building is finished?
It is repaid or converted. A bank loan may convert to a term loan or be refinanced by a permanent mortgage; SBA 7(a) amortizes over up to 25 years plus the construction period (13 CFR 120.212). On a 504 project, the debenture is sold after completion and its proceeds repay the interim lender (SBA SOP 50 10 8.1).
Sources
- eCFR / FDIC: 12 CFR Part 365, Appendix A: Interagency Guidelines for Real Estate Lending Policies (accessed November 1, 2026)
- eCFR / FDIC: 12 CFR 324.2, definition of high volatility commercial real estate (HVCRE) exposure (accessed November 1, 2026)
- eCFR / FDIC: 12 CFR 324.32(j), HVCRE risk weight (accessed November 1, 2026)
- eCFR / FDIC: 12 CFR 323.3, appraisals required (accessed November 1, 2026)
- eCFR / SBA: 13 CFR Part 120, Business Loans (120.131, 120.151, 120.160, 120.212, 120.214, 120.910, 120.920, 120.931) (accessed November 1, 2026)
- U.S. Small Business Administration: SOP 50 10 8.1, Lender and Development Company Loan Programs (effective October 1, 2026) (accessed November 1, 2026)
- U.S. Small Business Administration: 504 loans (program page) (accessed November 1, 2026)
- U.S. Small Business Administration: 7(a) loans (program page) (accessed November 1, 2026)
- U.S. Small Business Administration: SBA Doubles Cumulative 7(a) and 504 Loan Limit to $10 Million (news release 26-52, May 18, 2026) (accessed November 1, 2026)
- Board of Governors of the Federal Reserve System: H.15 Selected Interest Rates, October 30, 2026 (accessed November 1, 2026)
- Federal Reserve Bank of New York: Secured Overnight Financing Rate (SOFR), October 29, 2026 (accessed November 1, 2026)
- FDIC: Quarterly Banking Profile, Second Quarter 2026 (accessed November 1, 2026)
- Board of Governors of the Federal Reserve System: Senior Loan Officer Opinion Survey on Bank Lending Practices, July 2026 (accessed November 1, 2026)
- Rider Levett Bucknall: Quarterly Construction Cost Report, North America, Q3 2026 (accessed November 1, 2026)
- U.S. General Services Administration: PBS 1000.6B (P120), Cost and Schedule Management Policy Requirements (accessed November 1, 2026)